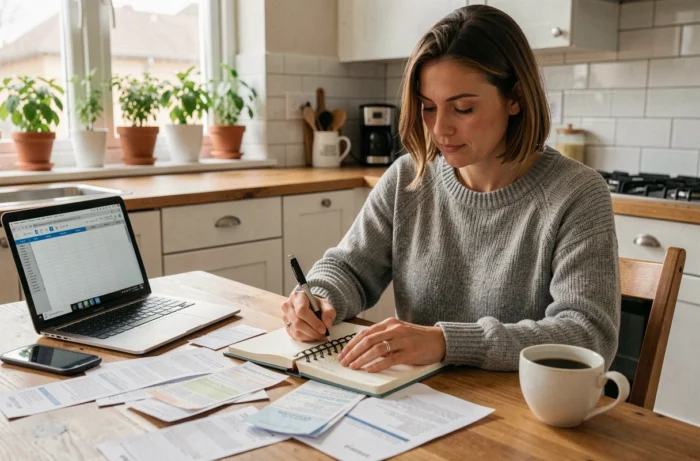
The savings rate of French households has been contracting since the start of the 2026 school year, according to Insee, and the priority is shifting from accumulation to preserving a precautionary reserve. Managing your budget on a daily basis now requires working on specific levers, not vague principles. Here are ten concrete actions, listed without hierarchy, to save sustainably.
1. Audit recurring payments line by line
Most bank statements contain payments whose origin the account holder has forgotten. We recommend a quarterly review, statement by statement, isolating each line whose label does not correspond to an actively used service.
An unrecognized payment must lead to a dispute with the bank within thirteen months of the debit. Beyond that, the recourse becomes more complex. Specialized resources in budget management are available at https://www.economielogique.com/, particularly to identify these invisible leaks.
2. Exercise the right to cancel annual contracts for telecoms and insurance
Since the law on cancellation in three clicks, terminating a telecom or internet subscription no longer requires a registered letter. The cancellation button must be accessible online, directly from the customer area. This lever remains underutilized by households that renew their contracts out of inertia.
In insurance, the annual cancellation allows changing auto or home contracts at any time after the first year. Comparing guarantees with equivalent coverage, rather than the face price, avoids losing protection for what is gained in premium.
3. Build a precautionary reserve before saving for the long term
Insee, in its economic note of September 10, 2026, forecasts a decline in purchasing power and a decrease in the savings rate. Trying to fund a retirement savings plan or a life insurance contract when the precautionary reserve is insufficient exposes you to overdraft in case of unforeseen events.
Three months of fixed expenses in an accessible savings account constitute an operational floor. The Livret A and the LDDS serve this role: immediate liquidity, guaranteed capital, no exit fees. According to Le Monde (September 23, 2026), regulated savings have seen a recent inflection after several months of outflows, a sign that households are becoming aware of this need for reserves.
4. Isolate the food budget with a physical envelope
Cash stuffing involves withdrawing in cash the amount allocated for food, then distributing it into envelopes by week. This is not a gimmick: switching to physical payment mechanically reduces impulsive spending because the constraint is visible and tactile.
We observe that this method works especially well for variable expenses (groceries, dining out, leisure). It loses its effectiveness on fixed charges that are automatically deducted, hence the importance of combining it with the audit of payments described above.
5. Plan meals weekly to eliminate waste
Food waste represents a silent loss item in the family budget. Establishing a weekly menu, then deriving a comprehensive shopping list, eliminates duplicate purchases and perishable products forgotten in the refrigerator.
Planning also allows concentrating purchases into one or two trips to the store per week. Fewer trips mean fewer temptations outside the list. Batch cooking (preparing meals in bulk on Sundays) extends this logic by reducing reliance on prepared meals, which are significantly more expensive per equivalent portion.
6. Renegotiate the rates of your ongoing loans
A mortgage or consumer loan taken out at a rate higher than current market conditions deserves a review for renegotiation or refinancing.
The cost of the operation (early repayment fees, processing fees, guarantees) must be included in the calculation. A comparative amortization table over the remaining term allows you to verify that the net gain is real. Do not rely solely on the nominal rate: it is the APR that includes all fees.
7. Automate a savings transfer on payday
Saving what is left at the end of the month does not work. The behavioral bias is documented: spending adjusts to the available balance. An automatic transfer scheduled on payday, even a modest one, reverses the logic.
Starting with a small amount and gradually increasing it each quarter avoids the frustration effect. The Insee economic survey published on September 24, 2026, shows that households view their future savings capacity less favorably, which reinforces the importance of automating this discipline before budget constraints worsen.
8. Compare insurances with strictly equivalent guarantees
Home, auto, and health insurance contracts often renew automatically without competition. The comparison should focus on the details of the guarantees:
- Amount of deductibles per claim, not just the annual premium amount
- Compensation limits by category (theft, water damage, civil liability)
- Waiting periods and specific exclusions in the contract
A low premium with high deductibles costs more at the first claim than a slightly higher premium with lower deductibles. The annual cancellation facilitates changing, but the comparison work remains the responsibility of the insured.
9. Bundle and reduce digital subscriptions
Video streaming, music, press, cloud, fitness apps: the stacking of subscriptions at a few euros per month can exceed several dozen euros per month without the household being aware of it.
We recommend listing each active subscription with its monthly cost and actual usage frequency over the past thirty days. Any service not used at least once a week deserves a suspension or cancellation. Bundled offers sometimes allow keeping two services for the price of one and a half subscriptions.
10. Track the evolution of the family budget with a dedicated tool
A spreadsheet or budgeting app is not meant to record past expenses. Its real utility is to project the balance over thirty days by incorporating upcoming payments, expected income, and planned exceptional expenses.
- Categorize each expense as fixed charge, variable charge, or exceptional expense
- Compare the projected budget to the actual one each month, item by item
- Identify recurring discrepancies to adjust the envelopes the following month
Monthly tracking transforms budget management into an iterative process. Without this feedback loop, good resolutions remain theoretical. The tool matters less than the regularity: a simple file updated weekly outperforms a sophisticated app consulted once a quarter.
Budget management is not a rigid discipline. In a context where purchasing power remains under pressure, every lever activated, even modestly, contributes to maintaining a financial buffer that will become precious in the coming months.